

Start here — a reader-first snapshot
If you’re ready to grab your first digital line of credit, this is written for you: practical, clear, and focused on steps that actually matter. DiDi’s lending arm is aimed at riders and gig workers who want quick access to cash with minimal fuss — see details at didi prestamos — and I’ll walk you through what to expect from application to approval, including what can speed things up or slow them down.
How DiDi Finanzas generally works
DiDi Finanzas packages short-term loans and lines of credit through a mobile-first flow. You typically provide ID, a selfie for KYC verification, and basic bank or payout details. The process leans on automated underwriting and credit scoring algorithms to set an interest rate or APR and a loan term that fits your profile. Because it’s mobile-driven, decisions can be fast — but speed shouldn’t trump understanding the cost of credit.
Essential requirements to qualify
Expect these basics: a valid government ID, proof of income or recent payouts from the DiDi platform, a linked bank or digital wallet, and a mobile number tied to your account. Credit score expectations vary; some applicants get an offer with limited history if other signals — consistent ride income or platform activity — look solid. Prepare documents that show steady earnings and clear bank statements to avoid delays in underwriting.
Common mistakes and better choices
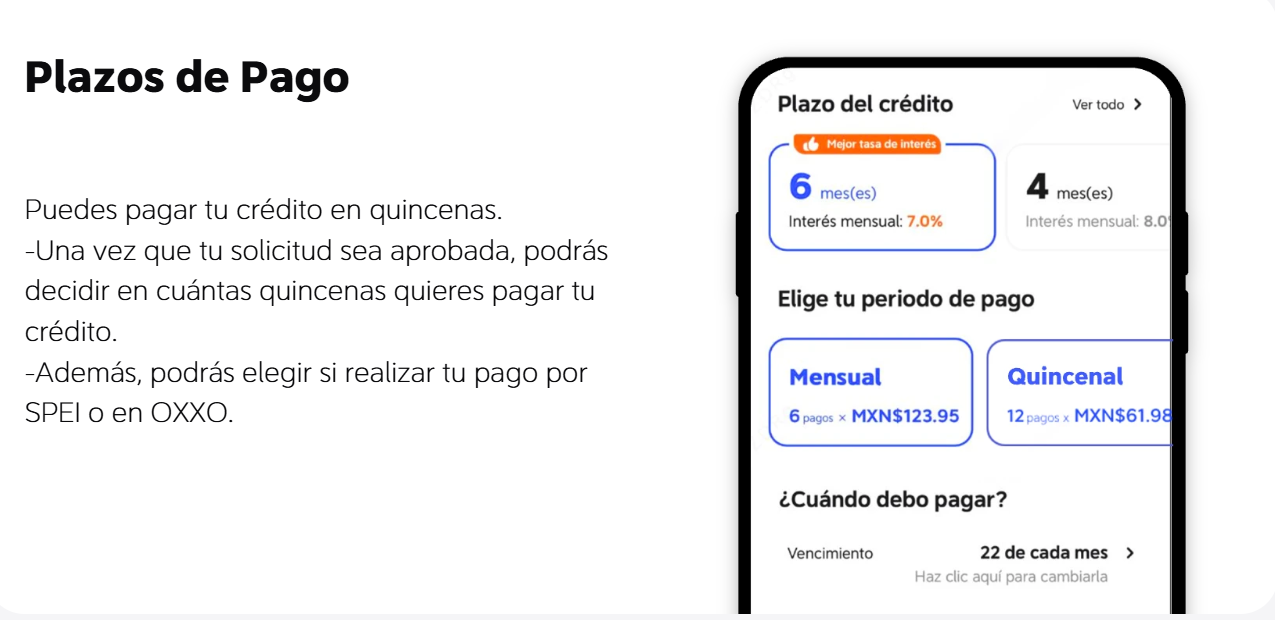
Many first-time borrowers chase the quickest approval and miss hidden costs. Watch the APR and any origination fees. Also, mixing repayment dates with your cash flow can cause trouble — align the loan term with times you actually get paid. Alternatives matter: compare DiDi offers with other creditos en linea available to gig workers and traditional microloans from local credit unions. Sometimes slightly higher monthly cost is worth it for better flexibility or a longer loan term.
Practical checklist before you apply
– Verify your DiDi account is active and in good standing.
– Consolidate last three months of bank or platform payout statements.
– Update contact info and prepare a clear photo of your ID and a selfie for KYC.
– Decide on a repayment schedule that matches expected income and avoids overdrafts.
These steps shave days off processing time and reduce the chance of a conditional approval that stalls the payout — small admin work, big payoff.
Real-world context and safety pointers
The shift to mobile lending accelerated after the 2020 lockdowns, when riders in cities like Mexico City depended on fast, digital cash options. That reality pushed lenders to tighten fraud controls and speed up KYC, but it also raised scrutiny around fees. Keep records and screen captures of offers, repayment terms, and any messages from the lender. If something looks inconsistent with the quoted interest rate or fees, escalate through in-app support and keep a dated trail.
Three golden rules for choosing and using a digital line of credit
1) Prioritize total cost over headline convenience — compare APR and fees, not just the monthly amount. 2) Match loan term to predictable income cycles to avoid missed payments and extra penalties. 3) Validate identity checks and document uploads before you hit submit to avoid manual review delays that can push disbursement days out.
Closing take
DiDi Finanzas fits a real need for gig workers who want fast access to capital without a bank branch — it’s practical when you prepare the right docs and watch APR and repayment cadence. Trust the process, but verify the numbers; this reduces surprises and keeps your credit score steady. — DiDi Finanzas.
